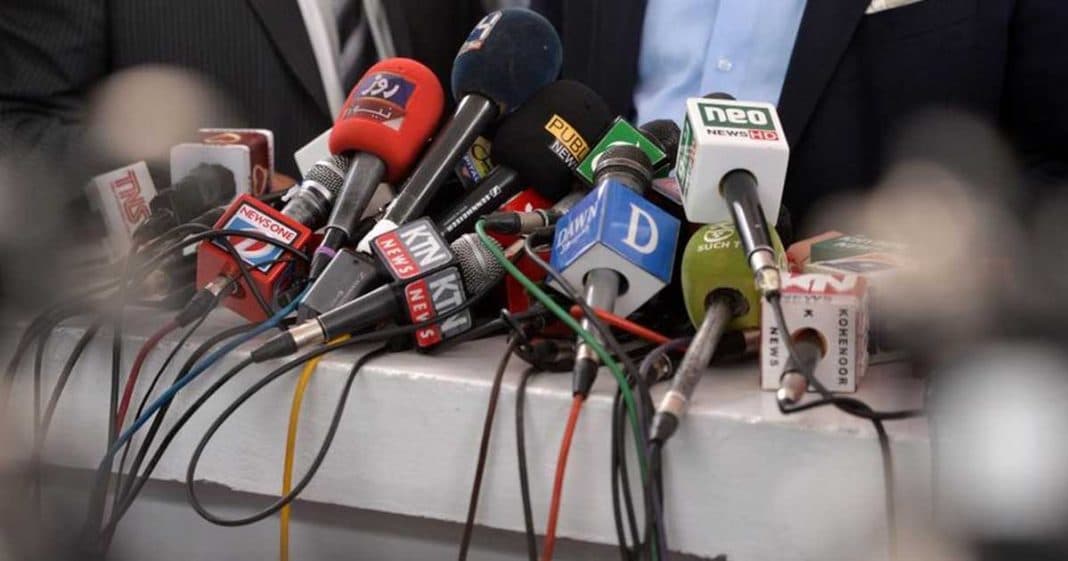
Traditional broadcasting in Pakistan and across much of South Asia, Africa, and parts of the Middle East has always carried an aura that extends far beyond commerce. Television channels have not simply been businesses; they have been symbols of influence, visibility, and in many cases, prestige. The industry has long been associated with glamour — bright studios, well-known anchors, high-profile political talk shows, and the sense that owning a channel is a direct line to public relevance. Yet behind this surface of excitement lies a far more difficult commercial reality that is now becoming impossible to ignore.
Across my own professional experience of more than two decades in international broadcasting, I have seen this pattern repeat itself in strikingly similar ways across geographies. Whether in Pakistan, the Middle East, Balkan states, or various African markets, television channels have often launched with significant enthusiasm and equally significant financial backing. I have also seen multiple channels operating from free zones in the Gulf, sometimes clustered within the same buildings, each launched with ambition, optimism, and confidence in rapid audience capture. In many cases, those same corridors now carry a very different atmosphere — spaces once associated with energy and ambition now appearing underutilised, with channels either shut down or struggling to remain operational.
The optimism trap
Far too often, broadcasters enter the market with optimistic projections that assume rapid audience growth and immediate advertising success. These assumptions rarely survive contact with market realities. Studies from the Project Management Institute consistently show that while a majority of projects may achieve some of their objectives, only around 40 to 50 percent fully meet their original time, cost, and scope baselines. When absolute success is defined as delivering exactly on all planned parameters, the figure drops dramatically to approximately 2.5 percent. Many media ventures implicitly plan as though perfection in execution is the expected outcome.
Nowhere is this more visible than in Pakistan's television industry. Many small and mid-sized broadcasters enter the market believing that licensing, infrastructure, and a modern studio setup will naturally lead to audience traction and advertising revenue. However, broadcasting is not an infrastructure business; it is a complex ecosystem business. It requires not just transmission capability, but sustained content investment, deep audience understanding, diversified monetisation, and disciplined financial control.
The dependency on government advertising
One of the most persistent vulnerabilities in Pakistan and similar markets is the heavy dependence on a narrow base of advertisers. Government advertising, in particular, has historically played a significant role in supporting broadcasters. Between July 2024 and March 2026, for example, the federal government of Pakistan spent over Rs9.28 billion on television, digital, and print advertising. While such spending provides short-term liquidity to the industry, it also introduces structural dependence. When a significant portion of revenue is tied to a single buyer, financial stability becomes highly sensitive to policy changes, budgetary adjustments, or shifts in political priorities.
This dependence has a second-order effect often discussed privately but less frequently acknowledged publicly. When broadcasters rely heavily on government or politically connected advertising, editorial independence can become difficult to sustain in practice, even if it is formally preserved. In some cases, advertising allocation itself becomes a point of leverage, subtly influencing programming decisions, tone, or coverage priorities. The risk is not always direct interference; more often it is structural vulnerability that shapes behaviour over time.
The digital disruption
At the same time, the global economics of broadcasting have undergone a structural shift. Digital platforms now compete directly for advertising budgets that once flowed predominantly to television. Global advertising expenditure is increasingly concentrated in digital ecosystems dominated by platforms such as Google, Meta, TikTok, Amazon, and streaming services such as Netflix. This shift reflects not just a change in format, but a change in philosophy: advertisers now prioritise targeting precision, real-time analytics, and measurable return on investment over mass reach alone.
For broadcasters in Pakistan and similar markets, this shift demands a redefinition of identity. A television station can no longer operate as a purely linear broadcaster. It must evolve into a multi-platform content organisation capable of producing not just television programming, but also digital video, podcasts, newsletters, documentaries, live events, educational content, and subscription-based services. Diversification into sponsorships, branded content, licensing, training, events, and digital subscriptions is no longer optional; it is structural necessity.
Building resilience
Ultimately, the most important lesson for broadcasters is that sustainability cannot depend on favourable conditions. It cannot rely on preferential advertising allocation, political alignment, or temporary market enthusiasm. A viable media organisation must be built on competitive content, diversified revenue streams, operational discipline, and genuine audience value.
The broadcasting industry in Pakistan and across similar markets still holds enormous potential. The demand for credible information, trusted journalism, and high-quality entertainment has not diminished. What will define the next phase of broadcasting is not who launches the most channels, but who builds the most resilient models. The future will belong to those organisations that treat broadcasting not as a symbol of glamour or influence, but as a disciplined, data-driven, multi-platform business.